
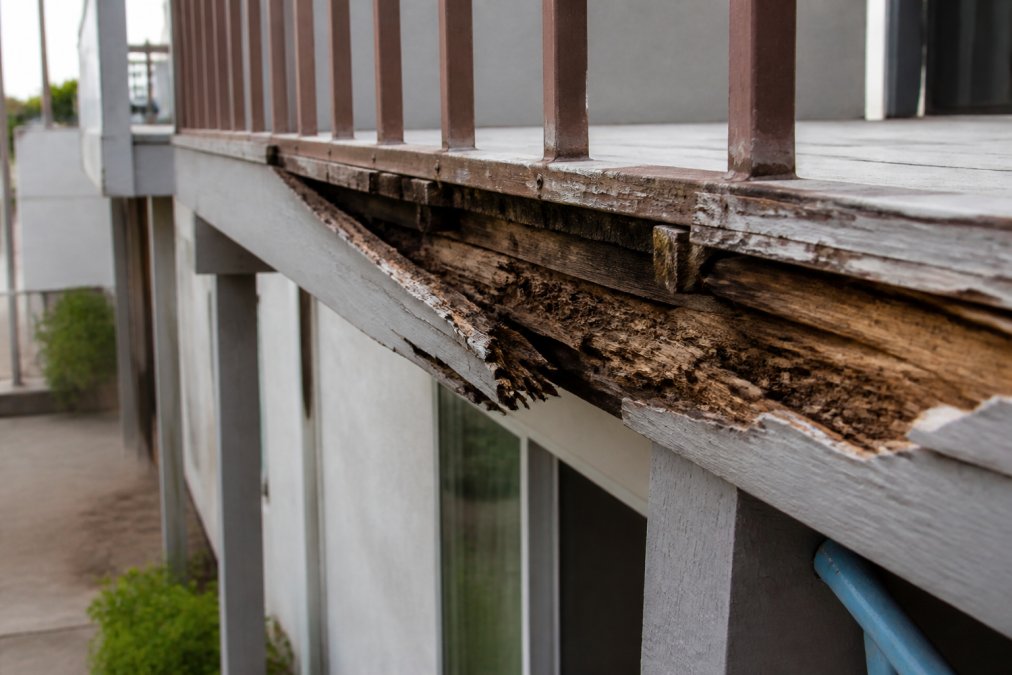
Table of Contents
- Why Balcony Wood Decay Rarely Qualifies as a Covered Peril
- When Accidental Water Damage Leads to a Successful Claim
- SB 326 Balcony Law Compliance and Your Insurance Obligations
- Signs of Structural Failure in Decks That Adjusters Look For
- Hiring a Licensed Balcony Inspector: What to Expect and Why It Matters
- Documentation, Mitigation, and Your Responsibilities After Discovery
- Conclusion
- Frequently Asked Questions
Last Updated: September 10, 2026
Why Balcony Wood Decay Rarely Qualifies as a Covered Peril
The short answer is that balcony wood decay is almost never covered, because homeowners insurance is built to pay for sudden, accidental events, not the slow breakdown of materials over time. This guide from Apex Balcony walks through where that line sits, why claims fail, and how to protect your building either way.
Rot is a process, not an event. It starts with a small moisture infiltration point, a failed sealant joint or a hairline crack in the stucco, and it works inward for years before anyone notices. By the time a board feels soft underfoot, the damage has usually been developing for a long time, and that timeline is exactly what sinks most claims.
A common mistake is assuming that because the balcony is attached to an insured structure, everything on it is covered. It isn’t. Policies cover the structure against named perils, and gradual deterioration is not one of them.
Sudden Damage vs. Gradual Deterioration: The Line Insurers Draw
The dividing line is time and cause, not severity. A windstorm that tears a railing loose on a Tuesday afternoon is a sudden event. Fungal growth that has been quietly consuming a floor joist for six years is gradual deterioration, and it is excluded in standard policies.
| Scenario | How Insurers Classify It | Typical Outcome |
|---|---|---|
| Windstorm rips off railing and flashing | Sudden, accidental | Covered, subject to deductible |
| Pipe bursts and soaks the deck boards | Sudden, accidental | Often covered |
| Rot from a failed sealant joint | Gradual deterioration | Denied |
| Termite damage discovered during inspection | Pest-related exclusion | Denied |
| Rot spreading from an unrepaired leak | Maintenance negligence | Denied |
The single most expensive mistake is delaying repairs after a small leak. Once water has been allowed to sit, insurers can point to maintenance negligence, and that denial follows the property into future claims.
When Accidental Water Damage Leads to a Successful Claim
Accidental water damage is the one path where a decay-related claim can succeed, provided the water event itself was sudden and the damage was reported promptly. A supply line that fails behind a wall, a washing machine hose that bursts on an upper floor, or a blocked drain that overflows onto a deck all qualify as sudden and accidental.
What makes these claims work is a clean chain of causation. You need to show that the water event happened at a specific time, that it was not the result of neglect, and that the resulting damage was discovered and reported without unreasonable delay. Photographs, a plumber’s invoice with a date, and a written timeline do more for a claim than any amount of explanation.
The moment you know about a leak and do nothing, the classification shifts. Insurers call this failure to mitigate, and it converts a covered event into a denied one. If you find water damage, stop the source, document everything, and start drying immediately.
SB 326 Balcony Law Compliance and Your Insurance Obligations
For buildings with three or more multifamily dwelling units in California, SB 326 balcony law compliance is not optional, and it intersects with insurance in ways most boards don’t anticipate (leginfo.legislature.ca.gov). The statute requires periodic inspection of exterior elevated elements, balconies, decks, stairways, and walkways, by a licensed professional, on a recurring cycle tied to the building’s original certificate of occupancy (leginfo.legislature.ca.gov). SB 721 applies a similar inspection duty to certain residential buildings outside the common-interest development structure. If you are unsure which statute applies, that determination depends on building type, ownership structure, and unit count, so confirm it with the agency that administers the requirement rather than guessing.
Here is the part that catches people off guard: compliance and coverage are separate questions. Passing an inspection does not guarantee a claim will be paid, and failing to inspect does not automatically void your policy. What non-compliance does is hand an insurer a ready-made argument about maintenance negligence if something fails later. In practice, the inspection report becomes evidence, either that you exercised reasonable care, or that you had notice of a condition and did nothing.
How Code Compliance and Coverage Interact
A frequent misconception is that because a repair is required by code, insurance must pay for it. Standard homeowners and commercial property forms generally separate the cost to repair covered damage from the cost to bring the undamaged portion up to current code. Many policies include some ordinance-or-law coverage, but the limit is often a small percentage of the dwelling limit, and it typically applies only when a covered peril caused the loss in the first place. If the underlying cause is gradual decay, the code-upgrade question is moot, there is no covered loss to attach it to.
A common pattern is that a wind claim tears flashing loose, water enters, and the resulting rot is discovered during the repair. The sudden wind event is the covered peril; the rot that predated it is not. The carrier may pay to repair the wind damage and the code-required reconstruction of that specific area, while denying the broader decay remediation. That split is why the cause-of-loss determination matters more than the size of the repair.
What the Inspection Report Does for a Future Claim
The role of home inspections in future claims is worth understanding now. If you sell the property, or if a future claim arises, a documented inspection history demonstrates that you exercised reasonable care. An absence of records does the opposite, and insurers read silence as neglect. A report that notes a condition and recommends repair is not automatically fatal, what matters is whether you acted on it. A dated repair invoice following a flagged finding is strong evidence of maintenance; a flagged finding with no follow-up is the fact pattern that supports a denial.
Inspection compliance protects you legally. Documentation protects you at claim time. You need both, and one does not substitute for the other.
state agency that administers exterior elevated element inspection requirements
Signs of Structural Failure in Decks That Adjusters Look For
Adjusters and inspectors look for the same things, and most of them are visible before a probe ever touches the wood. Soft or spongy decking underfoot, a railing that moves when you lean on it, rusted or pulling fasteners, and dark staining around the base of posts are the classic early indicators. What separates a paid claim from a denial is not how bad the damage looks, it is how the adjuster classifies the cause and whether the damage is structural or cosmetic.
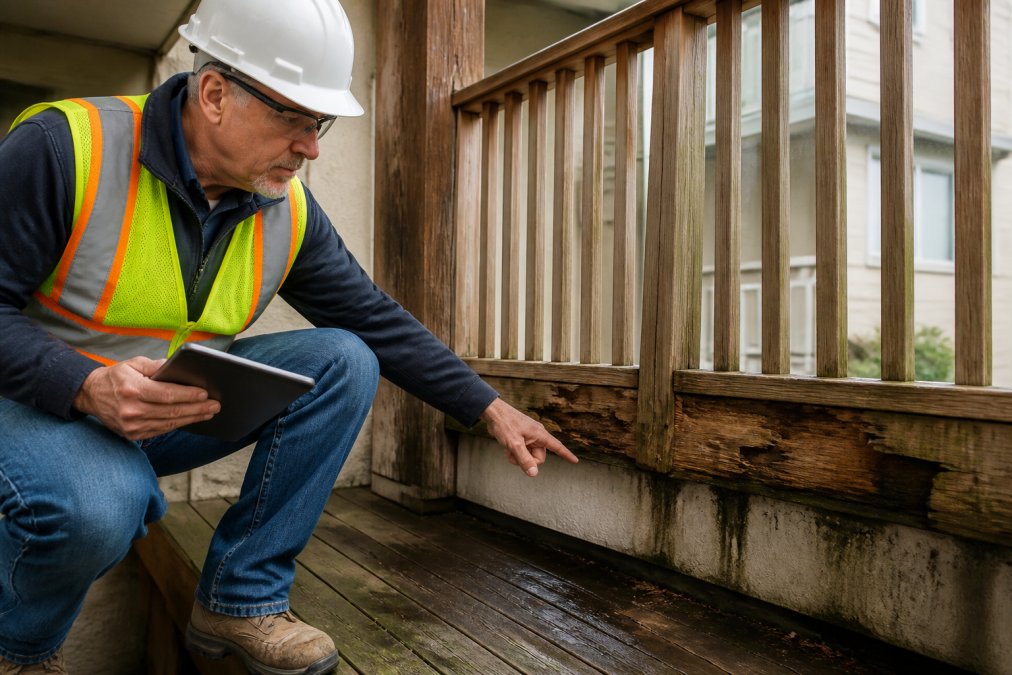
The Cosmetic vs. Structural Distinction
The distinction that matters most is between structural integrity and cosmetic rot. Surface discoloration on a fascia board or a weathered handrail is a cosmetic issue, and cosmetic rot is almost never covered because it is gradual deterioration. Rot that has reached a ledger board, a floor joist, or a post base is a structural one, and it is the difference between a repair and a replacement. Even then, coverage turns on cause: structural rot from a sudden, accidental water event may be covered, while structural rot from years of failed sealant is excluded.
- Decking and trim: soft spots, cupping, and visible fungal growth
- Fascia and railing bases: staining, peeling paint, and crumbling edges
- Fasteners: rust streaks, backing-out screws, and loose connections
- Post bases: standing water, soil contact, and splitting
- Attachment points: gaps at the ledger board and movement in the framing
How an Adjuster Determines Cause of Loss
When a claim is filed, the adjuster’s job is to answer one question: what peril caused this loss, and is that peril covered? The mechanism usually works backward from the damage. Water staining that radiates from a single point suggests a sudden event; staining that follows a joint line or spreads evenly across a surface suggests long-term intrusion. Probing with a moisture meter and an awl lets the adjuster map the boundary between sound and decayed wood, and that boundary often reveals how long the moisture has been present.
A common pattern is that the adjuster finds the rot, then looks for the source. If the source is a failed sealant joint or a clogged drain that was never cleared, the file trends toward maintenance negligence. If the source is a burst supply line or a storm-driven breach, the file trends toward a covered accidental water loss. The same rotted joist can land on either side of that line depending on the documented cause.
Documentation and Mitigation After Discovery
Once decay is discovered, your obligations start immediately, and how you handle the next two weeks shapes everything that follows. Mitigation means preventing further damage, not fixing the balcony. Tarp the affected area, stop any active water intrusion, restrict access if the structure is compromised, and keep the receipts. Failure to mitigate converts a potentially covered event into a denied one.
Documentation is the other half. Build a file that includes dated photographs from multiple angles, moisture readings, the inspector’s report, contractor estimates, and a written timeline of when you noticed the problem and what you did about it. If a claim or a lawsuit follows, this file is your defense. Photograph the same locations every six months from the same angles, a dated progression series showing stable conditions is powerful evidence of responsible maintenance, and it takes ten minutes per inspection cycle.
The single most expensive mistake is delaying repairs after a small leak. Once water has been allowed to sit, insurers can point to maintenance negligence, and that denial follows the property into future claims.
Hiring a Licensed Balcony Inspector: What to Expect and Why It Matters
Hiring a licensed balcony inspector gives you a documented, defensible record of your building’s condition, which is the asset that holds up in an audit, a lawsuit, or a claim dispute. The inspection itself should be non-destructive wherever possible, using moisture meters, probes at suspect locations, and photographic documentation rather than wholesale tear-out.
What most guides miss is that the report is the deliverable, not the visit. A useful report identifies each elevated exterior element, records its condition with dated photographs, distinguishes cosmetic from structural findings, and recommends a repair priority. That document is what you hand to your insurer, your board, and your contractor.
This is where Apex Balcony operates. Our licensed inspectors bring decades of combined construction and design experience to each property, and we specialize in SB 326 and SB 721 compliance across balconies, decks, and stairways. We’ve worked with hundreds of building owners, and the pattern is consistent: the buildings that document early are the ones that avoid emergency spending later.
Pricing for an inspection depends on the number of units, the number of elevated elements, and site access, so we quote per property rather than publishing a flat figure. Request a quote and you’ll get a scope before anyone shows up.
Documentation, Mitigation, and Your Responsibilities After Discovery
Once decay is discovered, your obligations start immediately, and how you handle the next two weeks shapes everything that follows. Mitigation means preventing further damage, not fixing the balcony. Tarp the affected area, stop any active water intrusion, restrict access if the structure is compromised, and keep the receipts.
Documentation is the other half. Build a file that includes dated photographs from multiple angles, moisture readings, the inspector’s report, contractor estimates, and a written timeline of when you noticed the problem and what you did about it. If a claim or a lawsuit follows, this file is your defense.
Photograph the same locations every six months from the same angles. A dated progression series showing stable conditions is powerful evidence that you maintained the property responsibly, and it takes ten minutes per inspection cycle.
The role of home inspections in future claims is worth understanding now. If you sell the property, or if a future claim arises, a documented inspection history demonstrates that you exercised reasonable care. An absence of records does the opposite, and insurers read silence as neglect.
Conclusion
Balcony wood decay sits squarely in the gap between what insurance covers and what buildings actually need, and closing that gap is a documentation and maintenance problem more than a coverage problem. Apex Balcony helps California property owners meet SB 326 and SB 721 requirements with licensed inspectors who identify early signs of structural failure before they become emergencies. Book an inspection with Apex Balcony and get a clear, defensible record of your building’s condition, a documented path to necessary repairs, and the compliance evidence your board needs.
Frequently Asked Questions
Will insurance cover rotting wood on a balcony?
Standard homeowners insurance policies almost never cover balcony wood decay. Insurers classify rot as gradual deterioration, which is a policy exclusion. The exception is when rot results directly from a sudden, accidental event like a burst pipe or storm damage that created moisture infiltration. In that scenario, the resulting water damage may be covered, but the rot itself typically is not. Document the original event thoroughly to support any claim.
Is wood rot considered structural damage by insurance companies?
Insurance companies generally treat wood rot as a maintenance issue, not structural damage, even when it affects floor joists or load-bearing elements. This distinction matters because policies cover sudden structural damage from covered perils, not deterioration from neglect. However, if a covered peril caused the moisture that led to rot, the structural repair might qualify. An insurance adjuster will determine the cause of loss before deciding.
Does negligence affect insurance coverage for deck repairs?
Yes. If an insurer determines that maintenance negligence allowed wood rot to develop or worsen, they can deny the claim outright. Policies require homeowners to perform reasonable upkeep. Documented maintenance records, inspection reports, and prompt repairs strengthen your position. California’s SB 326 and SB 721 inspection requirements for multi-unit buildings add another layer, since non-compliance can also affect liability and coverage decisions.
What are the mandatory inspection requirements for elevated exterior elements?
In California, SB 326 requires HOAs to inspect elevated exterior elements like balconies, decks, and stairways every nine years by a licensed inspector. SB 721 requires owners of buildings with three or more dwelling units to inspect similar elements every six years. Both laws mandate that inspectors identify signs of structural failure and report findings. Compliance helps prevent claim denials tied to deferred maintenance and protects residents from preventable accidents.